By Thomas Brandt October 6, 2026
To increase merchant account processing limit capacity, contact your processor or acquiring-risk team before expected sales materially exceed the profile already approved for your MID. Be prepared to document current processing, projected monthly volume, average and maximum ticket, bank activity, the reason for growth, and your ability to fulfill the additional sales.
If Your Sales Will Exceed the Current Limit Soon, Do These 7 Things
- Confirm your approved monthly processing volume, average ticket, and maximum ticket.
- Calculate when projected sales are likely to exceed the current profile.
- Contact underwriting or the processor’s risk department before that happens.
- Ask exactly which documents are required for a limit review.
- Assemble current processing statements and financial records.
- Build a month-by-month forecast supported by actual business evidence.
- Get the revised approved profile in writing before relying on the higher capacity.
The important word is before. A merchant account volume increase request is easier to evaluate when underwriting sees the explanation before the transaction pattern changes rather than during a seasonal rush, major launch, or sudden ticket-size increase.
What Is a Merchant Account Processing Volume Cap?
A monthly processing volume cap is usually a processor- or acquirer-specific underwriting parameter associated with the merchant account. It is not one universal dollar amount imposed by Visa or Mastercard on every business.
During merchant underwriting, a processor or acquiring bank may evaluate an expected profile that includes:
- monthly and annual card sales;
- transaction count;
- average transaction size;
- maximum or high ticket;
- card-present versus card-not-present activity;
- ecommerce percentage;
- recurring billing;
- international activity;
- refund behavior;
- fulfillment periods;
- advance payments; and
- future-delivery exposure.
Not every provider literally uses the word “cap.” You may instead see expected monthly volume, approved monthly volume, monthly bankcard volume, sales volume, processing parameters, average ticket, high ticket, maximum ticket, or merchant profile.
A merchant-specific processing limit should not be confused with a universal Visa monthly cap. Under the Visa Core Rules and Visa Product and Service Rules, an acquirer must maintain a merchant agreement with each merchant, and that agreement governs the merchant’s obligations within the Visa acceptance relationship; the rules do not establish one standard monthly processing dollar limit for every merchant.
That distinction matters. An estimated sales field used for underwriting is not necessarily identical to a hard technical limit that automatically stops transactions.
Visa’s rules require an acquirer to maintain a merchant agreement with its merchants and establish broader responsibilities for card acceptance, risk management, and transaction processing. They do not create one universal monthly processing cap for all merchants.
Mastercard’s rules similarly place ongoing monitoring obligations on acquirers. Its February 2026 Security Rules and Procedures specifically address changes such as increases in merchant deposit volume, average ticket, transaction counts, refunds, chargebacks, and unusual activity.
During the original merchant account approval and underwriting process, expected monthly volume, average ticket, highest ticket, sales channels, fulfillment practices, and processing history can all help establish the account’s initial risk profile. If those assumptions later change materially, the merchant may need the profile reviewed again before relying on the higher activity.
Where to Find Your Monthly Processing Volume Cap and Average Ticket Limit
Before trying to increase merchant account processing limit capacity, find out what is currently approved.
Check:
- your original merchant application;
- merchant processing agreement;
- approval or onboarding notice;
- MID/account setup paperwork;
- processor dashboard;
- underwriting correspondence;
- risk-team emails;
- acquiring-bank documentation; and
- account-support records.
Do not assume the number shown on your dashboard is the underwriting limit. A dashboard may tell you how much you have processed this month without displaying the risk parameters associated with the MID.
Ask the processor this specific question:
“What monthly processing volume, average ticket, and maximum ticket are currently approved for this MID?”
Then ask whether each figure is:
- an estimate used for monitoring;
- an underwriting threshold;
- a contractual limit; or
- a technical hard limit.
Those answers matter because average ticket, maximum ticket, and monthly volume are different risk inputs.
The approved processing profile is also tied to the account created during onboarding. Merchant ID configuration can connect the approved merchant profile with gateway settings, terminals, settlement instructions, reporting, and other processing controls, which is why the MID is a useful reference when asking underwriting to confirm current volume and ticket parameters.
Increase Merchant Account Processing Limit Before Growth Reaches It
The strongest time to increase merchant account processing limit capacity is when the growth is foreseeable but has not yet materially changed your processing pattern.
Consider two situations.
Scenario A: Growth Is Explained Before It Happens
A merchant expects sales to increase because of a holiday season, new store, wholesale contract, advertising campaign, product launch, or geographic expansion.
The merchant submits a merchant account volume increase request, explains the business driver, provides supporting documents, and asks underwriting to approve the new profile before the higher sales begin.
That does not guarantee approval. It does give the risk team context.
Scenario B: Transaction Volume Suddenly Changes
The merchant starts processing materially larger batches without contacting underwriting.
The processor may see activity that no longer resembles the account’s historical or expected profile. Depending on the account, that can lead to a document request, manual review, funding review, reserve consideration, or re-underwriting.
None of those results is automatic.
| Situation | What the Risk Team Sees | Possible Merchant Experience | Better Approach |
| Pre-approved growth | Explained increase | Profile reviewed before growth | Submit request early |
| Unexplained growth | Material deviation | Possible risk review | Contact underwriting |
| Larger tickets | Higher per-sale exposure | More documentation may be requested | Explain ticket change |
| Seasonal spike | Temporary volume increase | Activity may look unusual | Provide seasonal forecast |
This comparison between expected and actual activity is especially visible on newer accounts. During the first 90 days of merchant-account processing, actual volume, average and highest ticket, refunds, disputes, sales channels, and fulfillment patterns may provide risk information that was not available when the application was originally approved.
The Documentation Package Underwriters Want to See
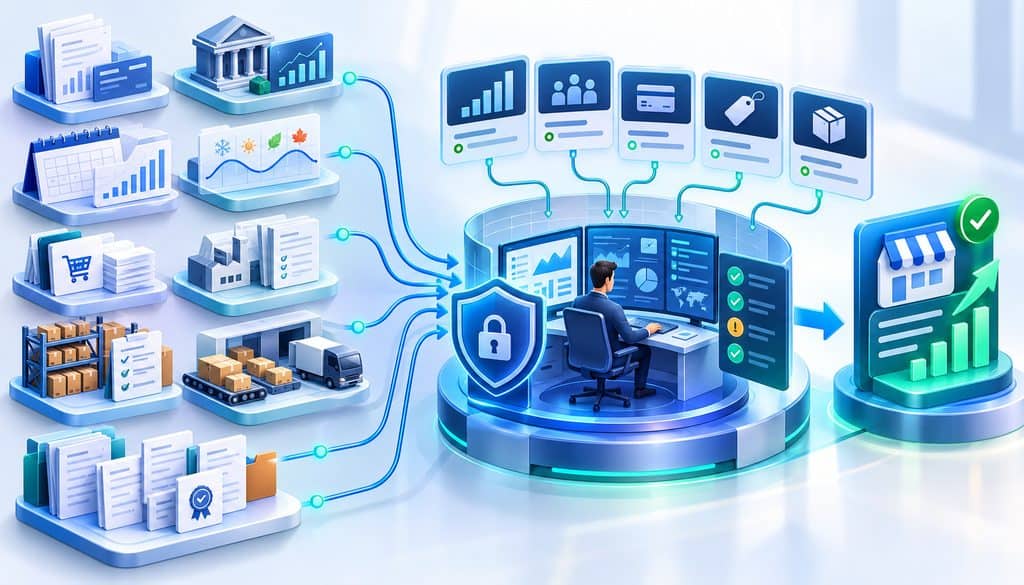
There is no universal document package for every underwriting review for higher volume. Requirements depend on the business, requested increase, acquiring bank, existing history, and exposure.
A useful package typically answers three questions:
- Why will sales increase?
- Can the merchant actually fulfill those sales?
- Can the business financially support the additional exposure?
| Document or Evidence | What It Helps Explain | What to Check |
| Processing statements | Existing volume and ticket behavior | Complete, consistent records |
| Business bank statements | Liquidity and operating activity | Correct business/entity |
| Sales forecast | Amount and timing of growth | Realistic assumptions |
| Customer contracts/orders | Evidence of expected demand | Valid dates and commitments |
| Supplier invoices | Inventory capacity | Connection to products sold |
| Fulfillment records | Ability to deliver | Realistic delivery periods |
| Historical sales | Seasonality | Comparable periods |
| Marketing evidence | Growth driver | Connection to forecast |
| Licenses/business records | Continued eligibility | Current versions |
Recent Processing Statements
Processing statements provide evidence of what the account is already doing.
An underwriter may look at:
- actual processing volume;
- transaction count;
- average ticket;
- refunds;
- disputes;
- recent growth; and
- sales stability.
Do not assume every processor universally requires three or six months. Supply the period actually requested.
Business Bank Statements
Bank records can help underwriting assess operating liquidity, financial stability, and whether business activity is consistent with the requested increase.
They may also help the reviewer assess whether the company appears able to support inventory purchases, payroll, refunds, disputes, and other obligations created by higher sales.
There is no universal minimum balance that guarantees approval.
Sales Forecast
The sales forecast deserves more attention than almost any other part of a merchant account volume increase request.
A useful forecast includes:
- current monthly card volume;
- expected gross sales;
- expected percentage paid by card;
- projected transaction count;
- expected average ticket;
- expected maximum ticket;
- month-by-month card volume;
- seasonal peaks; and
- the expected duration of the increase.
The numbers also need a reason.
“Sales should increase by 70%” is merely an estimate.
“November volume is projected to rise because of $90,000 in booked wholesale orders plus our normal holiday ecommerce demand” gives underwriting something it can investigate and understand.
Seasonality Evidence
For seasonal businesses, supporting information can include prior-year sales, reservations, booked projects, existing orders, historical revenue, or a recurring annual sales pattern.
If the business is new, do not manufacture a seasonal history. Explain what evidence supports the first-year forecast.
Supplier and Inventory Support
A processor may reasonably ask how the merchant intends to fulfill substantially greater sales.
Useful evidence can include:
- supplier invoices;
- purchase orders;
- inventory receipts;
- manufacturing capacity;
- warehouse capacity; or
- dependable supplier relationships.
If projected sales triple but inventory and fulfillment capacity remain unchanged, underwriting may naturally ask more questions.
Fulfillment Evidence
The time between payment and delivery matters.
A merchant selling merchandise across the counter presents a different exposure from a business collecting large prepayments months before fulfillment.
For businesses that collect money before completing the order, deposits and prepayments can change the underwriting exposure because higher processing volume may also increase the value of goods or services that customers have paid for but have not yet received. Longer delivery periods can therefore make fulfillment records and financial capacity more important during the review.
How to Build the Forecast for a Merchant Account Volume Increase Request
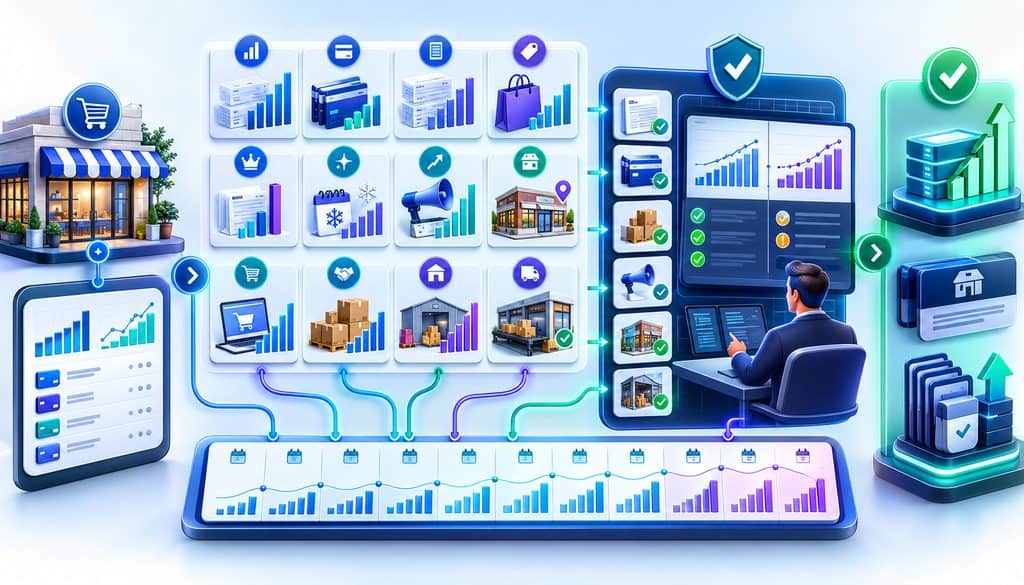
A good forecast does not need to be complicated. It needs to be explainable.
Step 1: Establish the Current Baseline
Calculate your recent:
- monthly processing volume;
- transaction count;
- average ticket;
- highest normal ticket;
- refund activity; and
- seasonal pattern.
Use actual processing data rather than memory.
Step 2: State the Increase You Need
Illustrative example only:
Current approved monthly volume: $150,000
Expected peak volume: $260,000
Requested processing capacity: $300,000
The requested amount should be related to realistic business needs rather than an arbitrary desire for “more room.”
Step 3: Forecast Month by Month
Illustrative example only:
| Month | Expected Card Volume | Transactions | Average Ticket | Main Driver |
| September | $155,000 | 2,000 | $77.50 | Baseline |
| October | $185,000 | 2,250 | $82.22 | Advertising |
| November | $235,000 | 2,850 | $82.46 | Holiday demand |
| December | $265,000 | 3,100 | $85.48 | Seasonal peak |
| January | $175,000 | 2,100 | $83.33 | Normalization |
This lets an underwriter distinguish a two-month spike from permanent growth.
Step 4: Explain Why Sales Are Increasing
Potential drivers include:
- holiday demand;
- new store;
- signed B2B agreement;
- product launch;
- marketing campaign;
- ecommerce expansion;
- larger distribution network; or
- new customer segment.
Connect each major projection to evidence where possible.
Step 5: Show That You Can Fulfill It
Document how staffing, inventory, production, warehouse capacity, suppliers, shipping, appointment capacity, or service capacity will scale.
Growth without fulfillment capacity can increase refund and dispute exposure.
Step 6: Separate Volume Growth From Ticket Growth
This is one of the most important parts of an underwriting review for higher volume.
Processing twice as much because customer count doubled is different from processing twice as much because individual transactions became twice as large.
Call out both.
Step 7: Attach Evidence
A spreadsheet becomes more credible when it connects to purchase orders, inventory, prior sales, signed contracts, bookings, advertising plans, or another genuine growth driver.
Raising Your Average Ticket Requires a Different Explanation
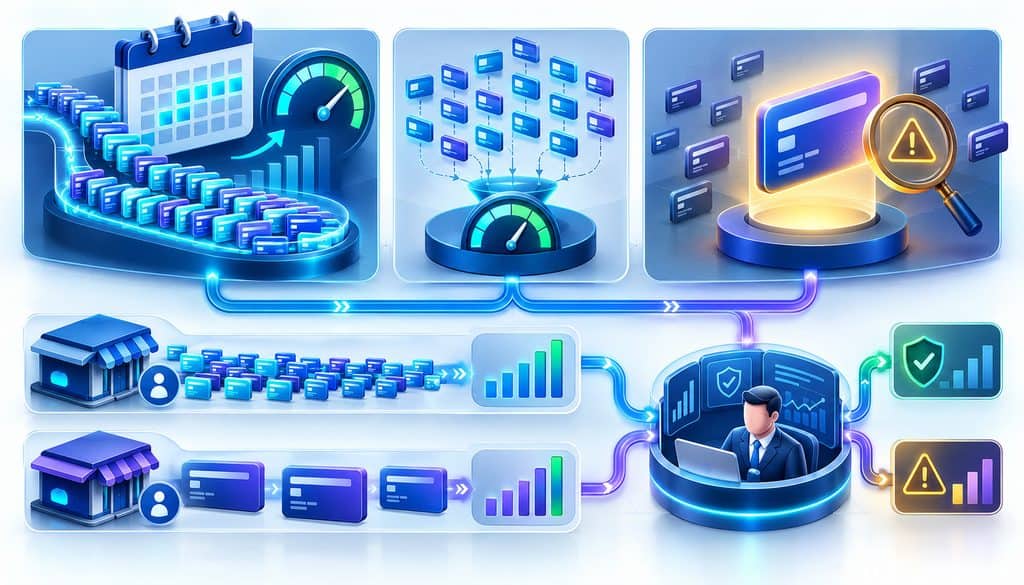
An average ticket increase request should not be treated as another name for increasing monthly sales.
Three different numbers may be involved:
Monthly processing volume: total card sales processed during the month.
Average ticket: average value of an individual transaction.
Maximum or high ticket: the largest transaction size expected or approved.
Consider two fictional merchants.
Merchant A increases monthly sales from $100,000 to $200,000 because it serves roughly twice as many customers. Average ticket remains approximately the same.
Merchant B also increases sales from $100,000 to $200,000, but transaction count barely changes because customers now make purchases approximately twice as large.
Merchant B has materially changed its per-transaction exposure.
For that reason, an average ticket increase request may require explanation of new premium products, B2B orders, annual billing, large deposits, custom projects, installment arrangements, or other high-ticket activity.
If you need to raise credit card processing limit capacity and increase the maximum ticket, tell underwriting about both changes. Do not assume approval of the monthly volume automatically changes the ticket profile.
How Far Before a Busy Season Should You Request the Increase?
There is no universal processor or card-network deadline for submitting a merchant account volume increase request.
The review period depends on the processor, acquiring bank, requested change, merchant history, industry, documentation, and whether follow-up information is needed.
Operationally, start once the higher volume becomes reasonably foreseeable.
Waiting until:
- the first unexpectedly large batch;
- the week before a launch; or
- after the current approved profile has already been exceeded
leaves less time to answer questions.
Ask underwriting:
- What documents are required?
- What is the current review turnaround for this account?
- Does the acquiring bank need separate approval?
- Will the request involve a reserve review?
- Does maximum ticket need separate approval?
- When will the updated profile become effective?
- How will approval be documented?
Treat any suggested planning period as operational guidance, not an industry rule.
What Underwriters Evaluate Before Approving Higher Volume
Processing History
A stable established account gives the reviewer real performance data.
That history can show whether the merchant has processed consistently, handled refunds appropriately, maintained predictable ticket sizes, and grown in an understandable way.
No specific number of months guarantees an approval.
Chargebacks and Disputes
An underwriter may consider dispute frequency, dispute amounts, reasons, recent trends, and the additional exposure created by projected growth.
Do not confuse card-network monitoring programs with the internal criteria used to increase merchant account processing limit capacity.
They are related to payment risk but serve different purposes.
Refund Activity
Refunds may be reviewed because they create financial obligations against previously processed sales.
An abrupt change can matter, especially if volume is rising at the same time.
There is no universal refund percentage that guarantees approval or denial.
Business Model
Underwriting can differ materially between:
- retail;
- ecommerce;
- subscription sales;
- travel;
- ticketing;
- custom manufacturing;
- professional services;
- digital products; and
- high-ticket B2B sales.
The type of business can change how long exposure remains outstanding and what documentation is useful.
Fulfillment Period
Future delivery can matter because a merchant may receive settlement long before the customer receives the promised product or service.
As that gap grows, the acquirer can have greater exposure if customers later seek refunds or file disputes.
Financial Capacity
A reviewer may examine liquidity, bank activity, financial history, capitalization, and the merchant’s ability to absorb legitimate refunds and disputes.
There is no universal minimum cash balance.
Average and Maximum Ticket
A substantial ticket-size change can alter the account’s risk even if projected monthly card sales appear manageable.
That is why a request to raise credit card processing limit capacity should clearly distinguish aggregate volume from transaction size.
What Makes a Request Easier or Harder to Underwrite?
| Factor | Lower-Concern Presentation | More Questions Likely |
| Growth | Gradual and explained | Sudden and unexplained |
| History | Established and stable | Very limited |
| Disputes | Stable | Increasing |
| Refunds | Consistent with model | Unexplained spike |
| Forecast | Supported | Speculative |
| Inventory | Capacity demonstrated | Supply unclear |
| Fulfillment | Proven process | Long or uncertain |
| Ticket size | Near historical pattern | Sharp increase |
| Financials | Consistent | Significant unexplained weakness |
This is a decision-support framework, not an approval formula.
One weakness does not automatically cause denial, and one strong characteristic does not guarantee approval.
What Happens If Sales Exceed the Approved Profile Before You Ask?
This is one of the most important distinctions in the article:
Exceeding an expected monthly processing amount does not mean Visa or Mastercard automatically freezes your money.
Depending on the account, a material change may instead lead to:
- document requests;
- verification of larger transactions;
- an updated financial review;
- underwriting reassessment;
- funding review;
- reserve consideration; or
- confirmation of the new business activity.
That monitoring is not hypothetical. Mastercard’s current Security Rules and Procedures for merchant monitoring require acquirers to monitor factors including increases in merchant deposit volume, average ticket size, transaction counts, refund activity, chargebacks, and abnormal increases in merchant activity.
For new merchants, Mastercard also calls for monitoring against expected turnover described in the business plan.
Mastercard’s current rules provide a useful example of why processors watch these changes. Acquirers are required to monitor merchant deposit volume, average ticket, transaction count, refunds, chargebacks, and abnormal or suspicious increases in activity.
That is different from saying Mastercard sets your monthly processing volume cap.
Do not respond by splitting sales among unrelated MIDs merely to stay below a threshold. If the business needs more processing capacity, address the underwriting issue directly.
What to Do If Only Part of the Increase Is Approved
Fictional example:
Requested capacity: $500,000 per month
Approved capacity: $350,000 per month
A partial approval is useful information.
Ask:
- What general concern limited the increase?
- Is the concern monthly volume or maximum ticket?
- Would additional financial information help?
- Would additional processing history support another review?
- Can the limit be increased in stages?
- Is a reserve option available?
- Is the approval temporary?
- When can the account be reviewed again?
The processor may not disclose proprietary risk scores. It may still explain the general category behind the decision.
Operate against the approved amount, not the amount originally requested.
If the Merchant Account Volume Increase Request Is Denied
Use a structured response:
- Ask which general risk category affected the decision.
- Identify whether missing evidence can resolve the concern.
- Ask whether a smaller increase could be approved.
- Ask whether the increase can be staged.
- Ask whether an appropriate reserve or another disclosed risk control is available.
- Reforecast expected sales against current approved capacity.
- Decide whether the existing acquiring relationship still fits the business.
Do not disguise the additional volume or route it through another MID solely to avoid monitoring.
A denial can result from insufficient history, financial exposure, unsupported growth, ticket size, fulfillment, disputes, industry fit, or another account-specific factor.
The objective is to identify what can realistically change.
When a Processing Cap Means You May Have Outgrown the Account
Repeatedly needing to increase merchant account processing limit capacity can eventually indicate that the underlying account structure no longer matches the business.
Possible signs include:
- sales permanently far above the original underwriting profile;
- repeated limit-increase requests;
- substantially larger maximum tickets;
- new international activity;
- major ecommerce expansion;
- new lines of business;
- different fulfillment periods; or
- an acquiring bank unwilling to support the merchant’s current scale.
That does not mean changing processors should be the first response.
First determine whether the current provider can re-underwrite the business properly.
If not, compare alternative acquiring relationships based on underwriting capacity, contract terms, reserve requirements, settlement structure, MID architecture, and the actual business model—not simply the advertised processing rate.
Example: Preparing for a Holiday Sales Surge
Consider an ecommerce merchant that normally processes about $120,000 per month.
Historical holiday demand plus recently signed wholesale orders indicate that November and December card volume could reach $220,000 to $260,000.
The existing approved profile does not comfortably support that level.
The Poor Approach
The merchant waits.
November sales accelerate and larger batches begin reaching the processor.
Risk staff request documentation during the busiest period of the year. The merchant then has to locate bank statements, processing history, supplier invoices, purchase orders, inventory evidence, and fulfillment records while trying to fill customer orders.
The transactions may be perfectly legitimate. The problem is that the change reached underwriting without context.
The Better Approach
The merchant prepares a merchant account volume increase request before the season begins.
It submits:
- historical processing;
- requested financial records;
- supplier invoices;
- purchase orders;
- inventory support;
- month-by-month projections;
- expected transaction counts;
- projected average ticket;
- expected highest ticket; and
- a fulfillment plan.
The merchant also identifies when seasonal processing volume should return toward normal.
That package does not guarantee the request will be approved. It does give underwriting more relevant evidence before the risk profile changes.
Sample Merchant Account Volume Increase Request
Subject: Request for Review of Approved Processing Volume – [Business Name]
Hello [Underwriting/Risk Team],
We are requesting a review of the currently approved processing profile for our merchant account.
Legal business name: [Legal Name]
DBA: [DBA]
MID/reference: [Reference requested by processor]
Current monthly card volume: [Amount]
Requested monthly card volume: [Amount]
Current average ticket: [Amount]
Expected average ticket: [Amount]
Expected maximum ticket: [Amount, if applicable]
Expected start date: [Date]
Forecast period: [Period]
The expected increase is related to [brief factual explanation].
We have attached the requested supporting records, including [documents].
Please let us know whether additional information is required. If approved, please provide written confirmation of the revised monthly volume and applicable average- or maximum-ticket parameters and the date the updated profile becomes effective.
Thank you,
[Name]
[Title]
[Business]
Volume Increase Underwriting Checklist
- Current approved processing profile confirmed
- Monthly processing volume cap clarified
- Projected monthly card volume calculated
- Average ticket recalculated
- Maximum ticket reviewed
- Seasonal volume documented
- Processing statements prepared
- Bank records prepared if requested
- Month-by-month forecast completed
- Growth driver explained
- Supplier/inventory support included where relevant
- Fulfillment capacity documented
- Refund trend reviewed
- Dispute trend reviewed
- Updated licenses included where relevant
- Secure submission method confirmed
- Written approval requested
Frequently Asked Questions
How do I find my merchant account monthly processing limit?
Review the merchant application, approval records, processing agreement, MID setup documents, portal, and underwriting correspondence. If the number is not visible, ask the processor what monthly volume, average ticket, and maximum ticket are currently approved.
Also ask whether each number is an expected underwriting assumption, monitoring threshold, contractual limit, or hard system restriction.
How do I increase my merchant account processing limit?
To increase merchant account processing limit capacity, request an underwriting review before expected sales exceed the current profile. Provide the processing history, financial records, sales forecast, growth explanation, average-ticket expectations, and fulfillment evidence requested by the reviewer. Ask for the updated approved profile in writing.
What documents help raise a credit card processing limit?
Documents may include processing statements, bank statements, customer contracts, supplier invoices, inventory records, sales forecasts, seasonal evidence, fulfillment documentation, and updated licenses.
The exact requirements depend on the processor and business. The best documentation explains both why sales are increasing and whether the merchant can financially and operationally support the increase.
How long does a merchant account volume increase request take?
There is no universal review time.
Turnaround depends on the processor, acquiring bank, merchant history, amount of the requested increase, industry, ticket-size changes, and whether additional documents are needed. Ask for the account-specific review expectation instead of relying on a generic industry estimate.
Can exceeding my processing limit cause held funds?
It can contribute to a funding or risk review in some circumstances, but it does not automatically mean settlement will be held. The outcome depends on the agreement, account configuration, transaction activity, processor, acquiring bank, and other risk factors.
Will the processor check chargebacks before increasing my limit?
It may.
Dispute history can help underwriting assess how much exposure higher sales could create. Reviewers may examine dispute amounts, frequency, trends, causes, refunds, fulfillment, ticket sizes, and overall account history. No single chargeback ratio guarantees approval.
Is an average ticket limit different from a monthly processing volume cap?
Yes.
A monthly processing volume cap deals with aggregate processing. Average ticket measures typical transaction size, while maximum ticket concerns the upper end of individual sales. An average ticket increase request may therefore require additional explanation even when total monthly volume remains manageable.
Raise the Limit Before the Sales Arrive
The best time to increase merchant account processing limit capacity is before the new transaction pattern arrives.
The practical workflow is simple:
- Know the existing underwriting profile.
- Forecast the growth.
- Contact the risk team early.
- Explain what is driving the increase.
- Document financial and fulfillment capacity.
- Address an average ticket increase request separately where necessary.
- Get the new approval in writing.
- Compare actual activity with the approved forecast.
A well-prepared request will not guarantee approval. It will give the underwriter a clearer, better-supported view of the business and reduce the chance that legitimate growth reaches the acquiring system without an explanation.
For PCI purposes, keep one final distinction clear: PCI DSS applies to merchants that store, process, or transmit cardholder data regardless of business size, while payment brands determine validation and reporting requirements. PCI transaction-volume classifications are therefore not the same thing as your processor’s approved monthly volume.
Information verified against current primary-source and card-network materials as of October 2026. Merchant underwriting limits, documentation requirements, funding controls, reserves, and approval timelines vary by processor, acquiring bank, merchant agreement, business model, and risk profile.