Getting approved for a merchant account is an important milestone, but approval does not necessarily mean underwriting is permanently finished. Once transactions begin flowing, the processor, acquiring bank, payment facilitator, or risk team can compare real activity with the business profile presented during onboarding. That comparison matters most when the...
Taking Deposits and Prepayments: How Card Rules Treat Money Collected Before Delivery, and the Documentation That Protects You
A card payment collected today for a product or service delivered weeks or months later creates a different risk profile from a normal same-day retail sale. The merchant receives money before completing its obligation, which makes clear customer authorization, delivery terms, refund policies, processor disclosure, and fulfillment records especially important....
Understanding Merchant Service Pricing Models
Merchant service pricing models can feel confusing because card acceptance costs are rarely made up of one simple fee. A business may see percentage rates, transaction fees, authorization fees, gateway fees, monthly fees, PCI compliance fees, chargeback fees, and other line items on the same merchant account statement. This guide...
Why Merchant Applications Get Declined
When a business applies to accept card payments, approval is not automatic. A payment processor, acquiring bank, or underwriting team must decide whether the business fits its risk standards, documentation requirements, and operating policies. That review can feel confusing, especially when the response comes back as a declined application with...
How Merchant Accounts Are Approved
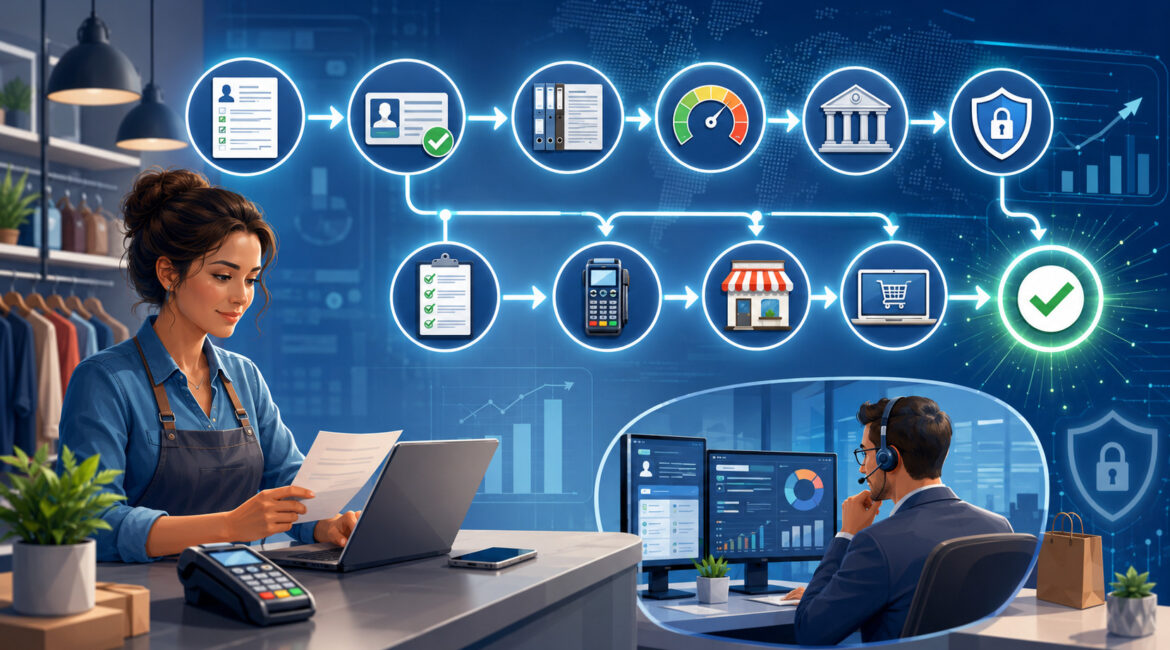
Merchant account approval is one of the most important steps a business takes before accepting card payments through a traditional merchant account. For many owners, the process can feel confusing at first because it involves forms, documents, verification steps, underwriting review, risk checks, and account setup. The good news is...